Tax Year in Income Tax: Meaning, Example, Start and End Date

Last updated: 23 July 2026 · Written and reviewed by CA Meet Dhrangadhariya, CSM & Co LLP

Quick summary

  • From 1 April 2026 the Income-tax Act, 2025 replaces the Income-tax Act, 1961.
  • The old Previous Year and Assessment Year are replaced by a single Tax Year of 12 months, from 1 April to 31 March.
  • Tax Year 2026-27 runs from 1 April 2026 to 31 March 2027. For a new business or source of income it starts on the date of setting up.
  • Income of FY 2025-26 (AY 2026-27) is still assessed under the 1961 Act, and the filing dates and process do not change.

The Income-tax Act, 2025 (Act 30 of 2025, which received assent on 21 August 2025) replaces both the “Financial Year (FY)” and “Assessment Year (AY)” with a single, unified concept called the “Tax Year”, which is a straightforward 12 month period from April to March, during which income will be earned and for which taxes are filed in the following tax year. This concept is effective from 01st April, 2026.

What is a Tax Year in Income Tax?

Tax year as per the Income Tax Act 2025 will replace the existing concept of Financial Year and Assessment Year. A Tax Year is a 12 month period that begins on the 1st of April and ends on 31st March of the following year. However, for newly established business and profession, the tax year starts from the date of establishment.

For example, Tax Year 2026-27 is a 12 month period which starts from 1st April 2026 and ends on 31st March 2027.

Earlier Law (Income-tax Act, 1961): Which Years were relevant?

Under the Income-tax Act, 1961, the concepts of Previous Year and Assessment Year were used.

  • Previous Year: Simply speaking, it is the year in which the income is earned. It can be less than 12 months in case the business is newly set up or the source of income is new. In those cases, the previous year is from the date of beginning of the new business/income source to March 31st.
  • Assessment Year: Simply speaking, it is the year in which the tax is paid for income earned. It is the year next to previous year. In assessment year, the income earned in previous year considered for tax purposes and tax is paid, if applicable.

This dual reference to years created a lot of confusion among tax-payers. Therefore, these concepts were revamped and the concept of “Tax Year” was introduced.

How are Previous Year and Assessment Year referred to in the Income-tax Act, 2025?

  • The new Act does not use the terms Previous Year and Assessment Year. Everything is expressed in terms of a Tax Year.
  • Section 263 of the Income-tax Act, 2025 deals with the return of income. Filing still happens after the end of the relevant tax year.

Can a Tax Year be less than 12 months?

Yes! Very much. As previously mentioned, a tax year can be less than 12 months in the following cases:

  • A new business or profession is set up in the middle of the financial year.
  • A new source of income set up in the middle of the financial year.

For example, a new business is set up on 01st June 2026, the tax year in this case would be from 01st June 2026 to 31st March 2027. Not 1st April to 31st March.

Comparison: Tax Year v/s Financial Year v/s Assessment Year

The comparison of tax year under the Income-tax Act, 2025 and Financial year and Assessment year is as follows:

Aspect Tax Year (New Law) Financial Year (Old Law) Assessment Year (Old Law)
Definition 12-month period for earning and reporting income 12-month period when income is earned The year following the Financial Year when tax is computed
Duration April 1 - March 31 April 1 - March 31 April 1 - March 31 (subsequent year)
Filing Period Tax is filed after the tax year ends Used to refer to income-earning period A tax return is filed in the AY
Example Tax Year 2026-27 (Income earned from April 1, 2026, to March 31, 2027) FY 2026-27 (Income earned from April 1, 2026, to March 31, 2027 AY 2026-27 (Tax return to be filed for FY 2025-26)

Will this Impact my Tax Filing?

  • Income earned in FY 2025-26 (AY 2026-27) is still assessed under the Income-tax Act, 1961. Tax Year 2026-27 is the first tax year under the new Act.
  • The removal of the concept of financial year and assessment year simplifies the tax process, giving taxpayers a better overview and lesser confusion.
  • It tends to simplify the operation of the tax authorities additionally by minimizing amounts of disparities and misinterpretations concerning assessment periods and the financial periods.
  • Therefore we can conclude that introduction of the concept of Tax Year does not change the dates of filing return, or the manner of filing. It has resulted in nothing but simplification of law and make it more accessible to public at large.

Final Word

The concept of tax year removes significant hurdles in understanding the tax laws, its applicability, relevant income and deductions. This is one of the most crucial changes made by the government, toward the goal of simplified tax laws and compliance.

Frequently asked questions

What is a Tax Year?

A Tax Year under the Income-tax Act, 2025 is the 12 month period from 1 April to 31 March in which income is earned. It replaces the Previous Year and the Assessment Year.

When does the Tax Year concept start?

It applies from 1 April 2026, so Tax Year 2026-27 is the first tax year under the new Act.

Can a Tax Year be shorter than 12 months?

Yes. For a business or profession set up during the year, or a new source of income, the tax year starts on the date of setting up and ends on 31 March.

Does the Tax Year change my return filing dates?

No. The introduction of the Tax Year simplifies the terminology but does not change the filing dates or the manner of filing.

Official sources

Related reading

Disclaimer

This article is for general informational purposes only and should not be considered professional advice. Please consult a qualified expert for advice tailored to your specific situation. The author and website owner are not liable for any errors or actions based on this content.

Section 80GGB and 80GGC: Deduction for Contributions to Political Parties

Last updated: 01 October 2026 · Written and reviewed by CA Meet Dhrangadhariya, CSM & Co LLP

Quick summary

  • Section 80GGB lets an Indian company deduct contributions to a registered political party or electoral trust, and section 80GGC allows the same for other assessees.
  • The contribution must be by any mode other than cash, and the whole amount qualifies, subject to the overall cap of gross total income.
  • The party must be registered under section 29A of the Representation of the People Act, 1951.
  • From Tax Year 2026-27 they are sections 136 and 137 of the Income-tax Act, 2025, and neither is available in the new tax regime.

The Income-tax law allows a deduction for money contributed to political parties and electoral trusts. Section 80GGB covers companies and section 80GGC covers everyone else. From Tax Year 2026-27 they are sections 136 and 137 of the Income-tax Act, 2025. For FY 2025-26 (assessment year 2026-27) they are still sections 80GGB and 80GGC of the 1961 Act.

Who can claim?

Section 80GGB (section 136) Section 80GGC (section 137)
Claimant An Indian company Any assessee other than a local authority and an artificial juridical person wholly or partly funded by the Government. Under the 1961 Act, companies were also excluded because they have section 80GGB
Recipient A political party registered under section 29A of the Representation of the People Act, 1951, or an electoral trust The same
Mode of payment Any mode other than cash Any mode other than cash
Amount The whole amount contributed The whole amount contributed

The 2025 Act does not repeat the 1961 Act’s exclusion of companies from the second provision. A company should still use section 136, which is its own provision.

What does “contribute” mean for a company?

For section 136 the word has the same meaning as in section 182 of the Companies Act, 2013. A company’s contribution is therefore more than a cheque to a party. It can include a donation, subscription or payment to a person for any activity meant to affect public support for a political party. Company law adds its own conditions. On 15 February 2024 the Supreme Court struck down the electoral bond scheme and also the 2017 amendments to section 182 of the Companies Act, 2013 that had removed the cap and the disclosure rule. As reported, this brings back the limit of 7.5% of the company’s average net profit of the preceding three years and the requirement to disclose the amount and the party in the profit and loss account. Confirm the current text of section 182 before a company contributes.

Limits

  • There is no separate percentage limit. The whole contribution qualifies.
  • The total of all deductions in Chapter VIII (including this one) cannot exceed gross total income (section 122(2) of the 2025 Act). A donation cannot create a loss.
  • No deduction is allowed for a cash contribution, in any amount.

Documents to keep

  • The party’s receipt or acknowledgement, showing the donor’s name, the amount, the date and the mode of payment.
  • The bank statement showing the payment by cheque, draft, UPI or transfer.
  • The party’s registration details under section 29A, to be sure the recipient qualifies.

Example

A partner of a firm has a gross total income of ₹9,00,000 and donates ₹30,000 by bank transfer to a registered political party. Under the old regime he claims ₹30,000 under section 80GGC (section 137), so his deduction is ₹30,000 and his income after this deduction is ₹8,70,000, before other deductions. Had he paid in cash, the deduction would have been nil.

Old regime only

Section 202 of the 2025 Act (the new regime) removes Chapter VIII deductions except sections 124(1), 124(2), 125(2) and 146. So sections 136 and 137 are not available in the new regime. Companies taxed at 22% or 15% (sections 200 and 201) also lose the deduction, since those regimes keep only sections 146 and 148.

Frequently asked questions

Who can claim section 80GGB?

An Indian company that contributes to a political party registered under section 29A of the Representation of the People Act, 1951, or to an electoral trust.

Who can claim section 80GGC?

Any assessee other than a local authority and an artificial juridical person wholly or partly funded by the Government (under the 1961 Act, also other than a company). It covers individuals, HUFs, firms, AOPs and BOIs.

Is there a limit on the deduction?

No separate limit. The whole contribution qualifies, but the total of all Chapter VIII deductions cannot exceed gross total income.

Can I pay in cash?

No. A contribution made in cash gets no deduction. Use a cheque, draft, bank transfer or another non-cash mode.

Can I claim it in the new tax regime?

No. Sections 136 and 137 of the 2025 Act are not among the Chapter VIII deductions kept by section 202, so they are available only in the old regime.

Official sources

Related reading

Disclaimer

This article is for general informational purposes only and should not be considered professional advice. Please consult a qualified expert for advice tailored to your specific situation. The author and website owner are not liable for any errors or actions based on this content.

Agricultural Income: Exemption, Partial Integration and Tax Calculation

Last updated: 07 September 2026 · Written and reviewed by CA Meet Dhrangadhariya, CSM & Co LLP

Quick summary

  • Agricultural income from land in India is not included in total income (Schedule II of the Income-tax Act, 2025, earlier section 10(1)).
  • It covers rent from agricultural land, income from farming and processing the produce to make it fit for market, income from farm buildings, and nursery income.
  • Tea, coffee and rubber income is split by Rule 271 of the Income-tax Rules, 2026, with 35% to 40% taxable as business income.
  • If net agricultural income exceeds ₹5,000 and other income is above the basic exemption limit, the exempt income raises the tax rate on the rest (partial integration).

Farm income is one of the oldest tax exemptions in India, because the Centre taxes income under Entry 82 of the Union List, which does not cover agriculture. From Tax Year 2026-27 the exemption is serial number 1 of Schedule II of the Income-tax Act, 2025 (it was section 10(1) of the 1961 Act), and the definition is in section 2(5).

What is agricultural income?

The Act defines it as:

  1. Rent or revenue from land situated in India and used for agricultural purposes.
  2. Income derived from such land by agriculture, by the process a cultivator or receiver of rent-in-kind ordinarily uses to make the produce fit to be taken to market (for example drying, cleaning, grading), or by selling that produce when nothing more than such a process has been done.
  3. Income from a farm building owned and occupied by the receiver of rent or revenue, or occupied by the cultivator, where the building is on or near the land and is needed as a dwelling house, store-house or other out-building because of the connection with the land. The land must be assessed to land revenue or a local rate, or, if it is not, it must not lie in a municipal or cantonment area above the population limits and distances in the definition of capital asset.
  4. Income from saplings or seedlings grown in a nursery.

The definition does not include income from a farm building or land that is used for something other than agriculture, including letting it for residential or business use. It also excludes income from transferring land that falls within the municipal limits and distance bands mentioned above.

What is not agricultural income?

The income has to come from land through agriculture, so these are taxed under other heads:

  • dairy farming, poultry, fisheries and bee-keeping,
  • income from timber or forest trees of spontaneous growth,
  • income from agricultural land held as stock-in-trade,
  • income from butter, cheese or similar factory processing separate from the farm,
  • dividends and remuneration that are merely calculated by reference to agricultural profits, and
  • agricultural income from land outside India, which is taxable for a resident.

Tea, coffee and rubber

Where the grower also processes the crop, part of the income is treated as business income. Under Rule 271 of the Income-tax Rules, 2026 (earlier Rules 7, 7A, 7B and 8), the share of income that is liable to tax is:

Income from Taxable as business income Agricultural (exempt)
Sale of tea grown and manufactured by the seller in India 40% 60%
Sale of coffee grown and cured by the seller in India 25% 75%
Sale of coffee grown, cured, roasted and ground by the seller in India, with or without chicory or flavouring 40% 60%
Sale of centrifuged latex, cenex, latex based crepes, brown crepes or technically specified block rubbers made from field latex or coagulum from rubber plants grown by the seller in India 35% 65%

An allowance is made for the cost of replanting dead or useless plants or bushes in an area already planted.

Partial integration of agricultural income

Agricultural income is exempt, but a person with substantial farm income and other income is not allowed to benefit from low slab rates twice. The method is laid down each year by the Finance Act. Section 3(2) of the Finance Act, 2026 applies it to Tax Year 2026-27, in both regimes, to an individual, HUF, AOP, BOI or artificial juridical person when:

  • net agricultural income is more than ₹5,000, and
  • non-agricultural income is more than the basic exemption limit.

The basic exemption limit is ₹4,00,000 for a person taxed under section 202 (the new regime). In the old regime it is ₹2,50,000 below age 60, ₹3,00,000 for resident seniors (60 to 80) and ₹5,00,000 for resident super seniors (80 and above).

Steps:

  1. Work out tax on non-agricultural income plus net agricultural income, at the slab rates.
  2. Work out tax on the basic exemption limit plus net agricultural income.
  3. Tax on total income is (1) minus (2), then rebate, surcharge and cess as applicable.

Example (old regime, individual below 60)

Non-agricultural income is ₹7,00,000 and net agricultural income is ₹2,00,000.

Step Amount in ₹
Tax on ₹9,00,000 (7,00,000 plus 2,00,000) 92,500
Tax on ₹4,50,000 (2,50,000 exemption limit plus 2,00,000) 10,000
Tax on total income (92,500 minus 10,000) 82,500
Cess at 4% 3,300
Total tax 85,800

Companies, firms, LLPs, co-operative societies and local authorities are outside this method.

Selling agricultural land

  • Rural agricultural land (not in the municipal and distance bands) is not a capital asset, so its sale gives no capital gain.
  • Land within those bands is a capital asset, and the gain is taxable and is not agricultural income. The bands are land inside a municipality or cantonment board area with a population of 10,000 or more, and land within 2 km (population above 10,000 to 1 lakh), 6 km (above 1 lakh to 10 lakh) or 8 km (above 10 lakh) of its limits.
  • Section 83 (section 54B of the 1961 Act) gives relief to an individual or HUF who sells land that the assessee, a parent or the HUF used for agriculture in the two years before the transfer and buys other agricultural land within two years after the transfer. The gain not exceeding the cost of the new land is not charged. A gain not used by the return due date has to be deposited in a specified bank or institution under the notified scheme.

Return filing

ITR-1 and ITR-4 cannot be used if agricultural income exceeds ₹5,000. Report it in the agricultural income schedule of ITR-2 or ITR-3 as applicable, and keep the evidence of the land and the produce.

Frequently asked questions

Is agricultural income taxable?

No. It is not included in total income (Schedule II, Sl. No. 1 of the Income-tax Act, 2025), but it is taken into account to work out the tax rate on your other income if it exceeds ₹5,000 and your other income is above the basic exemption limit.

Is income from agricultural land abroad exempt?

No. The definition covers land situated in India only.

Is dairy farming, poultry or fishing agricultural income?

No. The income must be derived from land by agriculture. These activities are taxed as business income.

Is the sale of agricultural land exempt?

Rural agricultural land is not a capital asset, so there is no capital gain. Land inside the municipal limits and distance bands in the definition of capital asset is a capital asset and the gain is taxable, with relief under section 83 if you buy new agricultural land.

Which ITR form do I use if I have agricultural income?

ITR-1 and ITR-4 cannot be used if agricultural income exceeds ₹5,000. Use ITR-2 or ITR-3 as applicable.

Official sources

Related reading

Disclaimer

This article is for general informational purposes only and should not be considered professional advice. Please consult a qualified expert for advice tailored to your specific situation. The author and website owner are not liable for any errors or actions based on this content.

Understanding Tax on ₹12 Lakh Income in India (Tax Year 2025-26)

Understanding Tax on ₹12 Lakh Income in India (Tax Year 2025-26)

Income tax can be confusing, especially when new rules come into play. Budget 2025 brought one of the biggest changes in personal income tax in recent years. If you earn ₹12 lakh a year, here’s what you need to know about your tax liability under the Income Tax Act 2025.

What’s Changed in 2025

The government revised the income tax structure effective for financial year 2025-26 (assessment year 2026-27). A key feature is the higher rebate and adjusted slab rates to boost disposable income for individuals. 

How Tax Works on ₹12 Lakh

Under the new tax regime:

  • Income upto ₹12 lakh is eligible for a full tax rebate under Section 87A, which essentially reduces your tax liability to zero. 

  • This means a person earning ₹12 lakh in a year does not pay any income tax if they choose the new tax regime. 

Here’s the idea:

  • The slabs start at zero tax for the first part of income.

  • Even though regular slabs would tax portions of income above ₹4 lakh, the rebate cancels the tax completely up to ₹12 lakh. 

This change is a major relief for middle-income earners and increases take-home salary. 

What Salary Earners Should Know

If you’re a salaried employee:

  • You receive a standard deduction (around ₹75,000) before calculating taxable income. 

  • After standard deduction, your taxable income might effectively fall below ₹12 lakh even if your gross salary is slightly above that.

  • In practice, many salaried individuals earning up to ~₹12.75 lakh also pay zero tax because of this deduction plus the rebate. 

Choosing Between Old and New Regime

You can choose between the old tax regime (with exemptions and deductions like 80C, HRA, 80D) and the new simplified regime. For someone at ₹12 lakh:

  • Under the old regime, you will have tax liability after standard slabs and only enjoy exemptions you claim.

  • Under the new regime, the tax rebate wipes out tax up to ₹12 lakh, making it generally more beneficial for many people without heavy deductions. 

Example in Simple Terms

Imagine your gross salary is ₹12 lakh:

  1. You get standard deduction (₹75,000 for a salaried person).

  2. Your taxable income becomes ₹11,25,000.

  3. Section 87A rebate cancels your tax liability on that amount under the new regime.

  4. Final tax payable is zero.

This drastically increases your monthly take-home pay compared to previous years.

Comparison Chart: Old vs New Tax Regime on ₹12 Lakh Income

Particulars

Old Tax Regime

New Tax Regime (2025)

Gross Annual Income

₹12,00,000

₹12,00,000

Standard Deduction

₹50,000

₹75,000

Income After Standard Deduction

₹11,50,000

₹11,25,000

Other Deductions (80C, 80D, HRA etc.)

Assumed ₹1,50,000

Not Applicable

Taxable Income

₹10,00,000

₹11,25,000

Tax Before Rebate

₹1,12,500 approx

₹56,250 approx

Section 87A Rebate

Not Available

Available up to ₹12 lakh

Final Tax Payable

₹1,12,500 + cess

₹0

Best Suited For

People with high deductions

Most salaried individuals


Tax Calculator Example: New Tax Regime (₹12 Lakh)

Step 1: Gross Income

₹12,00,000

Step 2: Standard Deduction (Salaried)

₹75,000

Step 3: Taxable Income

₹12,00,000 − ₹75,000 = ₹11,25,000

Step 4: Tax as per slabs

Tax calculated as per new slab rates

Step 5: Section 87A Rebate

Since taxable income is below ₹12,00,000, entire tax is rebated

Final Tax Payable

₹0


Tax Calculator Example: Old Tax Regime (₹12 Lakh)

Assumptions

  • Standard deduction: ₹50,000

  • 80C deduction: ₹1,50,000

Taxable Income

₹12,00,000 − ₹50,000 − ₹1,50,000 = ₹10,00,000

Tax Calculation

  • Up to ₹2.5 lakh: Nil

  • ₹2.5 lakh to ₹5 lakh: 5% = ₹12,500

  • ₹5 lakh to ₹10 lakh: 20% = ₹1,00,000

Total Tax

₹1,12,500

Plus 4% cess = ₹4,500

Final Tax Payable

₹1,17,000 approx


Key Takeaways

  • Under the new tax regime, income up to ₹12 lakh is completely tax free due to Section 87A rebate.

  • Salaried employees can effectively earn up to ₹12.75 lakh with zero tax because of the higher standard deduction.

  • The old regime only benefits those with large deductions like home loan interest or major investments.

  • For most individuals earning ₹12 lakh, the new tax regime is clearly more beneficial.


Final Thoughts

The 2025 tax changes are designed to benefit middle-class taxpayers by reducing or eliminating tax on incomes up to ₹12 lakh. For many people with this income level, the best option is the new tax regime with the rebate, especially if you don’t have large deductions to claim. 

Always consider using a tax calculator or consulting a tax professional to determine what’s best for your individual financial situation.

Section 80IA: Deduction for Infrastructure and Power Undertakings (Status for Tax Year 2026-27)

Last updated: 23 July 2026 · Written and reviewed by CA Meet Dhrangadhariya, CSM & Co LLP

Quick summary

  • Section 80IA gave a 100% profit-linked deduction for 10 years to undertakings in infrastructure, power, telecom and industrial parks.
  • It is now a closed window: infrastructure and power undertakings had to start before 01/04/2017, and the other categories ended earlier.
  • Undertakings already claiming it can continue for their remaining years under section 138 of the Income-tax Act, 2025, calculated as under section 80-IA.
  • It is not available if you are in the new tax regime or pay tax at the 22% or 15% company rates. The audit report is Form 10CCB, and Form 32 from 01/04/2026.

Section 80IA of the 1961 Act gave a 100% deduction of profits for 10 years to undertakings in infrastructure, telecom, industrial parks, and power. It was designed to attract private money into these sectors. The start dates in the section have long passed, so today it matters only for undertakings that started earlier and are still within their 10 year claim.

What changes from Tax Year 2026-27?

The Income-tax Act, 2025 does not re-write section 80-IA. Section 138 simply says that where an assessee is eligible to claim the deduction for a tax year “as if the said Act had not been repealed”, the deduction is allowed, calculated as under section 80-IA and only for the years section 80-IA would have allowed. For FY 2025-26 (assessment year 2026-27) the claim is still made under section 80-IA of the 1961 Act.

Which businesses qualified, and when did they have to start?

Business Had to start Deduction
Infrastructure facility (road, toll road, bridge, rail system, highway project, water supply, irrigation, sanitation, sewerage, solid waste, port, airport, inland waterway) Operation and maintenance on or after 01/04/1995 and before 01/04/2017 100% of profits for 10 consecutive years
Telecom services (basic, cellular, radio paging, satellite, trunking, broadband, internet) 01/04/1995 to 31/03/2005 100% for the first 5 years and 30% for the next 5
Industrial park or SEZ notified by the Central Government 01/04/1997 to 31/03/2006 (industrial parks to 31/03/2011) 100% for 10 consecutive years
Power generation, or generation and distribution 01/04/1993 to 31/03/2017 100% for 10 consecutive years
New transmission or distribution network 01/04/1999 to 31/03/2017 100% for 10 consecutive years, on profits from the new lines only
Substantial renovation and modernisation of an existing network (at least 50% increase in plant and machinery) 01/04/2004 to 31/03/2017 100% for 10 consecutive years
Revival of a power generating plant by a notified Indian company formed before 30/11/2005 Begins generating, transmitting or distributing before 31/03/2011 100% for 10 consecutive years

Which 10 years?

The assessee can choose any 10 consecutive years out of the first 15 years, counted from the year the undertaking starts. For infrastructure facilities that are roads, bridges, rail systems, highway projects, or water supply, irrigation, sanitation, sewerage and solid waste projects, the window is 20 years. Ports, airports and inland waterways keep the 15 year window.

Because of the start-date cut offs, the last possible year of a claim is, at the latest, FY 2035-36 for the 20 year infrastructure category and FY 2030-31 for other infrastructure and power generation. Telecom, SEZ, industrial park and power plant revival claims have run out.

Conditions

  • Infrastructure: the enterprise must be owned by a company registered in India, a consortium of such companies, or a body set up under a Central or State Act. It must have an agreement with the Central or State Government, a local authority or a statutory body to develop, or operate and maintain, a new facility.
  • Telecom and power: the undertaking must not be formed by splitting up or reconstructing an existing business, and must not be formed by transferring used plant or machinery to the new business. Used machinery up to 20% of the total value of machinery does not count against this.
  • Profits: for working out the deduction, the eligible business is treated as the only source of income of the assessee in its first year and in each later year. The deduction cannot exceed the profits of the eligible business.
  • Audit: the accounts of the undertaking must be audited and the audit report furnished in the prescribed form. That is Form 10CCB up to FY 2025-26, and Form 32 (Rule 66) under the Income-tax Rules, 2026 from 01/04/2026.

Which tax regime?

  • An individual, HUF, AOP, BOI or artificial juridical person can claim it only in the old regime. The new regime (section 202 of the 2025 Act) removes it.
  • A company can claim it only if it pays tax under the normal provisions. The 22% and 15% regimes (sections 200 and 201 of the 2025 Act) keep only sections 146 and 148 from the deduction chapter.
  • A co-operative society under the concessional rate (section 203) also cannot claim it.

Why not a “Section 80TTB” or “80IA form”?

Some older write-ups tell industrial park developers to follow “Section 80TTB” and to file an “80IA form”. Both are wrong. Section 80TTB is the senior citizen interest deduction, and there is no form called an 80IA form; the audit report is the form named above.

Frequently asked questions

Can a new infrastructure project claim section 80IA today?

No. The section does not apply to an enterprise that starts developing or operating the infrastructure facility on or after 01/04/2017. Power generation and transmission had to start by 31/03/2017 as well.

How long does the deduction last?

100% of eligible profits for any 10 consecutive years out of the first 15 years (20 years for roads, bridges, rail systems, highway projects and water and sanitation projects), counted from the year the undertaking starts.

What happens from Tax Year 2026-27?

Section 138 of the Income-tax Act, 2025 lets an eligible undertaking keep claiming, with the deduction calculated and limited to the years that section 80-IA would have allowed.

Is it available in the new tax regime?

No. The new regime for individuals and others (section 202) and the 22% and 15% company regimes (sections 200 and 201) bar this deduction.

Which audit report is needed?

Form 10CCB up to FY 2025-26, and Form 32 (Rule 66) under the Income-tax Rules, 2026 from 01/04/2026.

Official sources

Disclaimer

This article is for general informational purposes only and should not be considered professional advice. Please consult a qualified expert for advice tailored to your specific situation. The author and website owner are not liable for any errors or actions based on this content.

Filing of ITR after the Due date: Detailed legislative consequences, examples, and financial implications

Missing an income tax return due date under section 139(1) is not a harmless slip—it triggers a defined chain of statutory consequences spanning fees, interest, denial of benefits, assessments, penalties, and even prosecution. This blog compiles the relevant provisions, quotes key language from the Act for precision, and illustrates with worked examples so you can see the real money impact.

 Core filing obligation and timelines

Section 139(1): Who must file and by when 🗓️📄

“Every person,— (a) being a company or a firm; or (b) being a person other than a company or a firm, if his total income … during the previous year exceeded the maximum amount which is not chargeable to income-tax, shall, on or before the due date, furnish a return of his income … in the prescribed form and verified in the prescribed manner…” 🏛️📄

“Due date” includes, broadly: —

Sr. No. Due dates Required Assessees
1. 31st July or extended date For persons not required to get accounts audited 🗓️
2. 31st October or extended date For persons who are required to get accounts audited 🗂️
3. 30th November or extended date For persons who are covered by transfer pricing report requirements 🏢
  • Additional compulsions to file: 📝🔥 Separate provisos and notifications require filing even below the basic exemption in specified cases (e.g., foreign assets/signing authority; high-value transactions; section 139(1) fourth proviso for residents other than not ordinarily resident holding foreign assets).
  • Practical pointer: Total income for the threshold test is computed before giving effect to chapter VI-A deductions and certain exemptions. 🧮


What if you missed the due date?

Belated return window 🕰️🧾

Section 139(4): Belated return

“Any person who has not furnished a return within the time allowed to him under sub-section (1) may furnish the return for any previous year at any time before three months prior to the end of the relevant assessment year or before the completion of the assessment, whichever is earlier.”

  • Effect: You can still file, but you will pay late fee and interest, and you lose certain benefits tied to timely filing.

Section 139(5): Revised return 🔄✍️

“If any person, having furnished a return under sub-section (1) or sub-section (4), discovers any omission or any wrong statement therein, he may furnish a revised return … within the time allowed under sub-section (4).”

  • Effect: You can correct genuine mistakes, but only within the same reduced time frame (generally up to 31 December of the assessment year).

Section 139(9): Defective return ⚠️📄

“Where the Assessing Officer considers that the return of income furnished by the assessee is defective, he may intimate the defect … and if such defect is not rectified … the return shall be treated as an invalid return, and the provisions of this Act shall apply as if the assessee had failed to furnish the return.”

  • Effect: A defective return that is not cured becomes “non-filing” in law, with all attendant consequences.


Consequences that hit your pocket

Late filing fee

Section 234F: Fee for default in furnishing return

“Where a person required to furnish a return of income under section 139, fails to do so within the time prescribed … he shall pay, by way of fee, a sum of five thousand rupees: Provided that if the total income of the person does not exceed five lakh rupees, the fee payable shall not exceed one thousand rupees.”

  • Financial implication:
    • Income > ₹5,00,000: ₹5,000
    • Income ≤ ₹5,00,000: ₹1,000


Interest for delay and shortfall

Section 234A: Interest for defaults in furnishing return

“Where the return of income … is furnished after the due date … the assessee shall be liable to pay simple interest at the rate of one per cent for every month or part of a month comprised in the period from the date immediately following the due date to the date of furnishing of the return on the amount of the tax on the total income as determined … as reduced by [TDS/TCS, reliefs, advance tax, self-assessment tax already paid].”

  • Financial implication: 1% per month (or part) on net tax payable till the date you file.

Section 234B: Interest for defaults in payment of advance tax

“An assessee who is liable to pay advance tax … has failed to pay such tax or … the advance tax paid is less than ninety per cent of the assessed tax, shall be liable to pay simple interest at the rate of one per cent for every month or part of a month … from 1st April of the assessment year to the date of determination under section 143(1) or regular assessment.”

Section 234C: Interest for deferment of advance tax

Imposes 1% per month for shortfalls against every installments, (15 June, 15 September, 15 December, 15 March) based on prescribed percentages of “tax due on returned income.”

  • Financial implication: Even salaried taxpayers with significant “other income” can face 234B/234C if advance tax was not adequately paid.
  • Denial of carry-forward of losses ✋📉

Section 139(3) read with Section 80: Filing return to carry forward loss

“If any person has sustained a loss in any previous year under the head ‘Profits and gains of business or profession’ or under the head Capital gains and claims that the loss or any part thereof should be carried forward … he may furnish a return of loss … within the time allowed under sub-section (1) of section 139…”

“No loss which has not been determined in pursuance of a return filed in accordance with the provisions of sub-section (3) of section 139, shall be carried forward and set off …” (Section 80)

  • Exceptions: Carry-forward of house property loss [section 71B] and unabsorbed depreciation [section 32(2)] do not depend on timely filing.


Denial of certain deductions if filed late

Section 80C (and 10AA): Due date condition for key incentives

“Where … any deduction is admissible under any provision of this Chapter under the heading ‘C.—Deductions in respect of certain incomes’ … no such deduction shall be allowed unless the return of income for such assessment year is furnished by the due date specified under sub-section (1) of section 139.”

  • Effect: Deductions like 80-IA/80-IB/80-IC, 80JJAA, etc., and 10AA (SEZ) are lost if the return is not filed by the section 139(1) due date.


Option to tax regime and due-date linkage (business/profession) ⛔💼

Section 115BAC(5)/(6): Exercise/withdrawal of option

The option for individuals/HUFs having business or professional income must be exercised “on or before the due date specified under sub-section (1) of section 139” and is generally binding for subsequent years unless withdrawn per rules.

  • Effect: If you have business/professional income and miss the due date, your ability to choose the preferred regime for that year can be constrained by statute.


What the Department can do if you don’t file

Inquiry and best judgment

Section 142(1): Inquiry before assessment

“The Assessing Officer may serve on any person who has not made a return within the time allowed under sub-section (1) of section 139 a notice requiring him to furnish a return of his income … or to produce accounts or documents …”

  • Non-compliance penalty: Repeated failures can invite penalties under section 272A(1) (₹10,000 per default).


Section 144: Best judgment assessment

“If any person fails to make the return required under sub-section (1) of section 139 and has not made a return or a revised return under sub-section (4) or sub-section (5) of that section, [or] fails to comply with all the terms of a notice issued under sub-section (1) of section 142 … the Assessing Officer … after taking into account all relevant material … shall make the assessment of the total income … to the best of his judgment…”

  • Effect: Income can be estimated unfavourably; disallowances are common; protective additions may be made.


Reassessment exposure (if income has escaped assessment)

Section 148A/148: Notice and reassessment

If information suggests your income escaped assessment, the AO can (after following section 148A procedure) issue notice under section 148 requiring a return, even if you never filed originally.


Penalties and prosecution exposure

Under-reporting and misreporting

Section 270A: Penalty for under-reporting and misreporting of income

“The Assessing Officer … may direct that any person who has under-reported his income shall pay … a sum equal to fifty per cent of the amount of tax payable on under-reported income.” “In a case where under-reported income is in consequence of any misreporting … penalty shall be two hundred per cent of the amount of tax payable…”

  • Examples of misreporting: Misrepresentation or suppression of facts, failure to record investments, false entries, etc.
  • Prosecution for wilful non-filing

Section 276CC: Failure to furnish returns of income

“If a person wilfully fails to furnish in due time the return of income which he is required to furnish under sub-section (1) of section 139 … he shall be punishable,— (i) where the amount of tax, which would have been evaded if the failure had not been discovered, exceeds twenty-five lakh rupees, with rigorous imprisonment for a term which shall not be less than six months but which may extend to seven years and with fine; (ii) in any other case, with rigorous imprisonment for a term which shall not be less than three months but which may extend to two years and with fine.”

  • Important provisos:
    • No prosecution where tax payable on regular assessment is below the prescribed small amount threshold.
    • Filing after detection does not cure the offence; courts have upheld prosecution even if you later file.
 Updated return route if you missed income

Section 139(8A): Updated return; Section 140B: Tax on updated return

“Any person, whether or not he has furnished a return … may furnish an updated return … within twenty-four months from the end of the relevant assessment year.” “The person shall, before furnishing the updated return, pay the tax together with interest and fee … and the amount of additional tax payable shall be— (a) twenty-five per cent of aggregate of tax and interest, if furnished after the expiry of the time available under sub-section (4) or (5) of section 139 but before completion of twelve months …; (b) fifty per cent … if furnished after the expiry of twelve months but before twenty-four months …”

  • Exclusions: Not available in certain cases (e.g., search/requisition/survey cases, or where it results in refund/increased refund).


Worked examples with ₹ impact of non-filing ITRs within due dates:

Example 1: Late salaried filer with tax payable and no advance tax

  • Profile: Individual (non-audit), FY 2024-25 total income ₹12,00,000, tax payable on return ₹1,50,000 after TDS shortfall of ₹20,000, files on 31 October (3 months late).
  • 234F fee: ₹5,000 (income > ₹5 lakh).
  • 234A interest: 1% per month on unpaid self-assessment tax. Suppose net payable at filing is ₹20,000. For 3 months:

0.01×20,000×3=6000.01 \times 20{,}000 \times 3 = 600

  • 234B interest: Advance tax paid < 90% of assessed tax; interest 1% per month from 1 April to date of intimation/assessment on assessed tax minus prepaid taxes. If assessed tax is ₹20,000:

0.01×20,000×7 (April–Oct)=1,400

  • 234C interest: If quarterly advance tax installments were short, add typical few hundred to a couple thousand depending on timing.
  • Total extra cost (illustrative): ₹5,000 + ₹600 + ₹1,400 ≈ ₹7,000 plus any 234C.


Example 2: Investor misses due date and loses carry-forward

  • Profile: Individual with short-term capital loss ₹2,00,000 and small salary (TDS covers tax); files return on 15 November (belated).
  • Consequence: Under sections 139(3) and 80, the ₹2,00,000 capital loss cannot be carried forward. Future gains will be fully taxable without set-off.
  • Financial implication: If next year has ₹2,00,000 STCG at 15%, extra tax payable will be:

0.15×2,00,000=30,000 (+ surcharge/cess)0.15 \times 2{,}00{,}000 = 30{,}000\ (\text{+ surcharge/cess})

Example 3: Business assessee misses due date; deduction and regime impact

  • Profile: Proprietor claiming 80JJAA and considering regime choice; misses 31 October due date.
  • 80AC effect: Deduction under 80JJAA is disallowed for missing 139(1) due date—potentially large additional tax.
  • 115BAC(5) effect (business income): Option to choose applicable regime must be exercised on or before 139(1) due date; missing it can lock the assessee into the default rule for the year.

Example 4: Non-filing leads to best judgment and penalty

  • Profile: Professional with gross receipts ₹40 lakh does not file. AO issues 142(1) notice; no compliance; proceeds under 144, estimates income at 50% of receipts (illustrative) and levies 270A (under-reporting) on the difference.
  • Financial implication: Not only full tax plus 234A/B/C, but also 50% penalty on the “under-reported tax,” potentially adding lakhs.

Compliance checklist if you are already late

  • File the belated return under section 139(4):
    • Deadline: Generally, 31 December of the assessment year, or earlier if assessment completes.
    • Pay: 234F fee and compute 234A/B/C interest correctly.
  • If income was missed earlier, consider updated return under 139(8A):
    • Additional tax: 25% or 50% of tax+interest under section 140B, depending on timing.
    • Check ineligibilities before use.
  • Secure benefits that still survive a late return:
    • Carry-forward allowed: House property loss, unabsorbed depreciation.
    • Deductions unaffected by 80AC: General 80C/80D etc. can still be claimed if you file (but watch documentation and computation).
  • Respond promptly to any 142(1)/148A notices:
    • Avoid best judgment under section 144 and escalation to penalty/prosecution.
  • If business/profession:
    • Review 115BAC option timelines and document the chosen regime in the return or prescribed form.

Quick reference: sections and what they do

Section What It Does
139(1) Filing duties and deadlines 🗓️📄
139(3)/80 Carry forward losses’ rules 📉❌
139(4) Belated return deadline ⏳🧾
234F Flat late filing fee 💸💵
234A/B/C Interest for late/short tax payments 📈⏳
80AC/10AA Deduction forfeiture rules 💔🏦
142(1)/144 AO notices and assessments 📜⚖️
270A Penalty for under/misreporting 💸⚡
276CC Prosecution for non-filing 🚨🔒


If you have missed the due date for filing your tax returns then don’t worry but at the same time be cautious to file the belated tax returns. Filing belated return will attract certain penalties and interests but it will save you from various other proceedings.
Secondary Demat: A Simple Way to Cut Down Your Tax Bill

How Secondary Demat Account Can Save You Lakhs in Taxes

Zerodha has introduced a Secondary Demat Account feature – a huge win for investors who juggle both long-term holdings and short-term trades.

And if you don’t use Zerodha, no worries. You can still achieve the same benefit by simply opening two separate demat accounts with your broker instead of using just one. The idea is the same: keep investments and trades apart so your long-term gains don’t get taxed as short-term under FIFO rules.

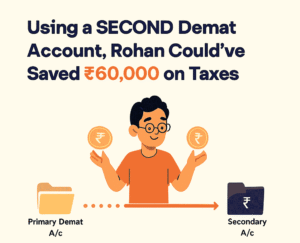
We analysed a case where investor Rohan (imaginary investor) ended up paying lakhs of extra tax only because all his shares sat in one account. With a secondary demat, that problem disappears.


The Problem with FIFO in a Single Demat

When you hold all your shares in a single demat, FIFO (First-In-First-Out) rules apply. This means whenever you sell, the system assumes you are selling the oldest lot first.

For active investors, this is a problem. Your long-term, low-cost investments often get sold “on paper” before your newer trades, pushing up your short-term capital gains (STCG) bill unnecessarily.


How Rohan Paid Extra Tax

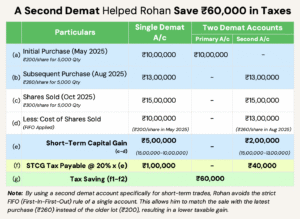
Let’s say Rohan made these trades:

  • May 2025: Bought 5,000 shares at ₹200 each → ₹10,00,000

  • August 2025: Bought another 5,000 shares at ₹260 each → ₹13,00,000

  • October 2025: Sold 5,000 shares at ₹300 each → ₹15,00,000

If all shares are in a single demat:

  • FIFO applies → May 2025 lot (₹200/share) is sold
  • Cost = ₹10,00,000

  • Sale = ₹15,00,000

  • Total Short-Term Capital Gain = ₹5,00,000

  • STCG Tax @ 20% = ₹1,00,000

If shares are split across two demats:

  • May 2025 lot sits in the primary account (kept as long-term investment)

  • August 2025 lot sits in the secondary account (used for short-term investment)

  • Sale in October is from the secondary account → FIFO applies here, so cost = ₹13,00,000

  • Sale = ₹15,00,000

  • Total Short-Term Capital Gain = ₹2,00,000

  • STCG Tax @ 20% = ₹40,000

Just by using a secondary demat, Rohan saves ₹60,000 in tax in a single transaction. 


Preserving Long-Term Gains

Now imagine if Rohan sells his May 2025 lot later in June 2026 at ₹350 per share:

  • Cost = ₹10,00,000

  • Sale = ₹17,50,000

  • Total Long-Term Capital Gain = ₹7,50,000

  • Taxed as LTCG @ 12.5% (after ₹1.25 lakh exemption) ≈ ₹75,000

Since he held the shares for more than 12 months, this qualifies as Long-Term Capital Gain (LTCG). Now, imagine if the same lot had been compulsorily sold earlier under FIFO rules. In that case, it would have been treated as Short-Term Capital Gain (STCG) and taxed at 20% – meaning a much higher tax outgo.


Why This Works

  • FIFO runs separately in each demat → your long-term and short-term positions stay ring-fenced.

  • Off-market transfers between your own demats are not taxable.

  • You still see both demats under one Zerodha Console login.


Costs and Caveats

  • AMC: Approx. ₹300 + GST per demat

  • Transfer Fee: Approx.₹25 + GST per off-market transfer
  • BSDA Loss: Holding more than one demat means you can’t claim BSDA (Basic Services Demat Account) benefits, which are meant for small investors with holdings under ₹2 lakh.


The Takeaway

With just one smart step – opening a secondary demat – Rohan:

  • Saved ₹60,000 immediately in October 2025
  • Preserved his long-term capital gains benefit instead of paying 20% STCG in June 2026

For active investors, this isn’t a one-time trick. Over time, keeping trades and investments in separate demats can help save lakhs in taxes year after year.


Disclaimer:

This article is for general informational purposes only and should not be considered professional advice. Please consult a qualified expert for advice tailored to your specific situation. The author and website owner are not liable for any errors or actions based on this content.

How the New Perquisite Rules Affect Your Salary Package (Notification 133/2025)

CBDT Notification No. 133/2025: Key Amendments under Section 17(2) of the Income-tax Act:

Comparison: Old Rule vs Amended Rule (2025)

Provision Amended Limit
(w.e.f. 18 Aug 2025)
Earlier Limit
Section 17(2)(iii)(c)

Taxability of perquisites for high-salaried employees

₹4,00,000

(salary income threshold)

₹50,000

(salary income threshold)

Proviso (vi) to Section 17(2)

Exemption for medical treatment abroad (travel condition)

₹8,00,000

(gross total income limit)

₹2,00,000

(gross total income limit)

Understanding Section 17(2)(iii)(c) & Proviso (vi) of the Income-tax Act, 1961

The Income-tax Act, 1961 lays down clear definitions of “salary,” “perquisites,” and “profits in lieu of salary.” Among these, Section 17(2) specifically defines perquisites. Over the years, perquisites have become a focal point in taxation, as they include various benefits provided by employers to employees apart from regular salary.

In this blog, we’ll break down Section 17(2)(iii)(c) and the Proviso (vi) to Section 17(2), examine their implications, and look at the latest amendments introduced in August 2025.


Section 17(2)(iii)(c): Value of Benefits or Amenities

According to Section 17(2)(iii), the value of any benefit or amenity granted free of cost or at a concessional rate is considered a perquisite. It applies in three scenarios:

  1. To a director of a company (clause a)

  2. To an employee holding substantial interest in the company (clause b)

  3. To any other employee whose income under the head “Salaries” (excluding non-monetary benefits) exceeds the prescribed threshold (clause c)

  • Earlier, this threshold was ₹50,000. However, as per the Income-tax (Twenty Second Amendment) Rules, 2025 notified via Notification No. 133/2025 dated 18th August 2025, the new threshold has been revised to ₹4,00,000 .
  • This means that only employees whose salary income (excluding perquisites) exceeds ₹4 lakh will have the value of employer-provided amenities taxed as perquisites.

Key Points:

  • Benefits like free housing, concessional loans, or luxury facilities will not be taxed as perquisites unless the employee’s salary income crosses ₹4 lakh.

  • Commuting facilities (like a company car used for home-to-office travel) remain outside the perquisite scope under this clause.


Proviso (vi) to Section 17(2): Medical Treatment Abroad

The provisos to Section 17(2) carve out certain exemptions where benefits provided by employers are not treated as taxable perquisites.

Under Proviso (vi), the following expenses are exempt from perquisite taxation if incurred by the employer:

  1. Medical treatment of the employee or family abroad

  2. Travel and stay abroad of the employee or family for such medical treatment

  3. Travel and stay abroad of one attendant accompanying the patient

Conditions for exemption:

  • The expenditure on medical treatment and stay abroad is exempt only to the extent permitted by the RBI.

  • The expenditure on travel abroad is exempt only if the employee’s gross total income (before including this expenditure) does not exceed the prescribed limit.

Previously, this limit was ₹2,00,000. But as per the as per the Income-tax (Twenty Second Amendment) Rules, 2025 notified via Notification No. 133/2025 dated 18th August 2025, for the purposes of Proviso (vi) to Section 17(2), the prescribed gross total income shall now be ₹8,00,000 .

This revision significantly broadens the scope of employees who can claim exemption for medical expenditure abroad.


Practical Implications of 2025 Amendment

For employees:

  • The perquisite taxation threshold under Section 17(2)(iii)(c) has increased from ₹50,000 to ₹4 lakh, reducing the tax burden on middle-income employees receiving non-monetary benefits.
  • For medical treatment abroad, the exemption limit has expanded fourfold from ₹2 lakh to ₹8 lakh, allowing more employees to claim relief.

For employers:

  • Salary structuring becomes more flexible — many perquisites will now escape taxation for employees with salaries below ₹4 lakh.
  • Medical support abroad provided by employers can now benefit a larger pool of employees without additional tax liability.

Conclusion

Section 17(2)(iii)(c) ensures that high-income employees pay tax on perks and benefits beyond their core salary, but the 2025 amendment has made the threshold more realistic by raising it to ₹4 lakh. Similarly, Proviso (vi) reflects the humane side of tax law, and the recent upward revision of the exemption limit to ₹8 lakh provides welcome relief for employees facing genuine medical needs abroad.

These changes balance the government’s aim of preventing tax-free luxury perks with providing much-needed support in health-related scenarios.

Read the source of this post by clicking here (Section 17 & Notification No. 133/2025)

Disclaimer:

This article is for general informational purposes only and should not be considered professional advice. Please consult a qualified expert for advice tailored to your specific situation. The author and website owner are not liable for any errors or actions based on this content.


Learn to Save Taxes on Your Trading Profits

How Traders Can Save Tax Through Eligible Business Expenses in ITR

In the fast-paced world of share trading, where profits and losses can swing dramatically, smart tax planning can significantly boost your net returns. If you’re a stock market trader dealing in Intraday or Futures & Options (F&O), understanding what expenses you can claim in your Income Tax Return (ITR) can help reduce your taxable income and legally save taxes.

Let’s explore how you can make the most of this benefit.

Who Can Claim Trading Expenses?

If you’re engaged in:
• Intraday Trading
• Futures & Options Trading (F&O)

…then you can claim eligible business-related expenses while computing your taxable income. This applies whether you follow the Old Tax Regime or the New Tax Regime.

Key Benefits for Traders

  1. Reduce Your Taxable Income: Legitimate trading expenses reduce your net business income, directly impacting your tax liability.
  2. Carry Forward of Losses:
    • F&O Losses: Can be carried forward for 8 years.
    • Intraday Losses: Can be carried forward for 4 years.

This makes it crucial to report your business income and expenses accurately.

Tax-saving tips for stock market traders: claim expenses on intraday and F&O trading, carry forward business losses, and maximize deductions under both tax regimes.

Common Expenses You Can Claim

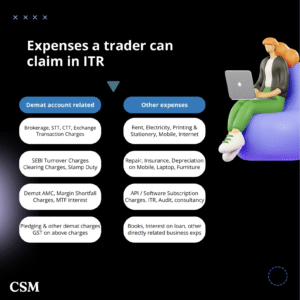
Here’s a sample list of expenses a trader can typically claim in the ITR:

Expense Category Examples
Internet & Phone Bills Broadband used for trading activities
Brokerage Charges Fees paid to brokers for executing trades
Software & Tools Charting tools, trading platforms, analytics tools
Advisory/Consulting Charges Subscriptions to trading advisories or analysts
Electricity If a home office is used for trading
Office Rent Applicable if a separate office is used
Depreciation On laptops, phones, and office equipment
Education & Seminars Trading courses or workshops attended
Books & Journals Financial newspapers, magazines, or books
Bank Charges Charges linked to your trading account

List of expenses a trader can claim in ITR - categorized into demat account-related and other business expenses

Note: Keep proper invoices, payment proofs, and usage justification for all claimed expenses. This is crucial in case of an audit.

What Expenses Cannot Be Claimed?

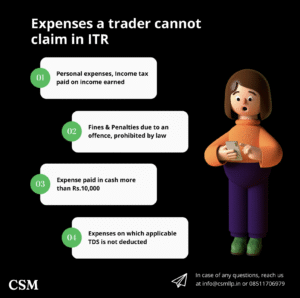
While many expenses are allowed, some are not claimable, such as:
• Personal expenses (e.g., personal phone bills, family subscriptions)
• Capital expenditures (unless depreciation is claimed)
• Any unrelated professional or personal expenses

Infographic showing a list of expenses that traders in India cannot claim as deductions in their income tax returns, including personal expenses, fines and penalties, cash payments above Rs.10,000, and expenses where TDS is not deducted.

Final Thoughts

Every saved rupee is an earned rupee. File smart, trade smarter!

Trading is not just about profits—it’s also about smart financial management. By claiming legitimate business expenses in your ITR, you’re not only reducing your tax outgo but also managing your business like a professional.

Disclaimer:

This article is for general informational purposes only and should not be considered professional advice. Please consult a qualified expert for advice tailored to your specific situation. The author and website owner are not liable for any errors or actions based on this content.


Required Documents for ITR compliances – FY 2024-25

Introduction

As financial year gets ended in the month of March, preparation for Income Tax Return (ITR) filing gets started where department and taxpayers both have to work upon various aspects. Department generally releases ITR forms during May or June and taxpayers compile the documents and rush towards their CAs for ITR compliances. Indian income tax law is considered to be one the most complex tax laws in the world and it is obvious that many complications will be faced by taxpayers for such ITR filing compliances.

To avoid unnecessary hustle, we have simplified the document compilation process for the taxpayers which can be very useful during ITR compliances. Documentary requirements for various ITR forms are different. It is best to discuss the summary of transactions carried out during the financial year with your CAs or advisors and they will suggest a proper ITR form to be filed based on the transactions carried out during the previous year.

Important Documents for ITR 1

Person required to file ITR 1 (Gross income upto ₹50 lac)

  1. Income from Salaries
  2. Income from House Property
  3. Income Other Sources
  4. Income from Long term capital gains (listed securities as per section 112A upto ₹1.25 lacs)

Required Documents for ITR 1

  1. PAN and Aadhaar number
  2. Form 16 from Employer
  3. AIS (Annual Information Statement) and TIS (Tax Information Statement)
  4. Interest Certificates for saving bank accounts
  5. Interest certificates and Account Statements for housing loan
  6. Profit and Loss statement for Demat Account (if any)

Note: Form 16 should be accompanied with Form 12BA for arriving the values of various perquisites which are included in the salary. Moreover, if there are more than 2 employers during a financial year or more than a single house property income then ITR 2 shall be applicable. Further, if any investments in foreign assest will be carried out during a financial year then also, ITR 2 will be applicable.


Important Documents for ITR 2

Person required to file ITR 2 (Gross income above ₹50 lac)

  1. Income from Salaries (more than 2 employers)
  2. Income from House Property (more than 1 house property)
  3. Income Other Sources
  4. Income from Capital gains (including crypto asset)

Required Documents for ITR 2

  1. PAN and Aadhaar number
  2. Form 16 from Employer
  3. AIS (Annual Information Statement) and TIS (Tax Information Statement)
  4. Interest Certificates for saving bank accounts
  5. Interest certificates and Account Statements for housing loan
  6. Profit and Loss statement for Demat Account (if any)
  7. Foreign Investment and Income statement
  8. Holding statement of Foreign Assets as on 31st December
  9. Profit and Loss statement of Crypto Assets
  10. Details of Capital Assests which are sold during previous year


Important Documents for ITR 3

Person required to file ITR 3

  1. All Income types as per ITR 2
  2. Income from Business and Profession

Required Documents for ITR 3

  1. PAN and Aadhaar number
  2. Form 16 from Employer
  3. AIS (Annual Information Statement) and TIS (Tax Information Statement)
  4. Interest Certificates for saving bank accounts
  5. Interest certificates and Account Statements for housing loan
  6. Profit and Loss statement for Demat Account (if any)
  7. Foreign Investment and Income statement
  8. Holding statement of Foreign Assets as on 31st December
  9. Profit and Loss statement of Crypto Assets
  10. Details of Capital Assests which are sold during previous year
  11. Financial Statements of the Business or Profession carried out during the previous year
  12. Capital account statement from the Firms in which partnership interest was available during previous year


Important Documents for ITR 4

Person required to file ITR 4

  1. All Income types as per ITR 1
  2. Income from Business and Profession – Presumptive Scheme benefit

Required Documents for ITR 4

  1. PAN and Aadhaar number
  2. Form 16 from Employer
  3. AIS (Annual Information Statement) and TIS (Tax Information Statement)
  4. Interest Certificates for saving bank accounts
  5. Interest certificates and Account Statements for housing loan
  6. Profit and Loss statement for Demat Account (if any)
  7. Financial Statements of the Business or Profession carried out during the previous year
  8. Capital account statement from the Firms in which partnership interest was available during previous year


Important Documents for Deductions

Taxpayers who are willing to opt old scheme of taxation shall be required to have following document while complying with ITR filing requirements.

Required Documents for claiming deductions under old scheme of taxation

  1. Invoice or Receipts to claim deductions under section 80C (such as LIC, PPF, NPS, Educational Fees etc)
  2. Health insurance invoice for claiming deduction under section 80D
  3. Interest certificates for claiming deductions under section 80E
  4. Donation receipts for claiming deductions under section 80G and 80GGC
  5. Invoice or Receipts for claiming any other deductions as per chapter VI of Income Tax Act, 1962


Conclusion

It is very important to figure out the proper ITR form to be required to file based on the transaction and nature of the activities carried out during the previous year. CAs or Advisors are the best person who will guide to determine the proper ITR form which should be filed based on the information made available to them. It is important to note that wrong selection of ITR will cause significant challenges where wrongly filed ITR would be considered as Defective ITR under section 139(9) of the Income Tax Act, 1962 and notice of the same would be issued to the taxpayers. Moreover, ITR should be filed within due dates mentioned under section 139(1) of the Income Tax Act, 1962 to carry forward the losses from business or capital gains for future years.


Disclaimer:

This article is for general informational purposes only and should not be considered professional advice. Please consult a qualified expert for advice tailored to your specific situation. The author and website owner are not liable for any errors or actions based on this content.